Table of Contents
TL;DR
Extra mortgage payments can cut years from a loan and save substantial interest, especially when rates are high. On a $300,000, 30-year mortgage at 7%, adding one extra principal-and-interest payment each year can eliminate the loan about six years early and save nearly $99,000 in interest. The decision still depends on your emergency savings, higher-interest debt, retirement match and need for accessible cash.
The Mortgage Math Most Homeowners Never Run
A mortgage payment can feel productive because it helps you stay in your home and slowly build ownership. But during the early years of a standard fixed-rate mortgage, most of the principal-and-interest payment may go toward interest rather than reducing the loan balance.
Consider a $300,000 mortgage at a fixed 7% rate for 30 years. The monthly principal-and-interest payment is approximately $1,996, not including taxes, homeowners insurance or homeowners association fees.
In the first month, about $1,750 goes to interest and only around $246 reduces principal. That means almost 88% of the first principal-and-interest payment goes toward interest. Over the first year, the homeowner pays approximately $23,369 in interest while reducing the mortgage principal by only about $4,582.
This is why extra payments can matter so much. Early additional principal reduces the balance before years of future interest are calculated on it.
How Extra Payments Build Home Equity
Home equity is the current market value of your home minus the mortgage and other debts secured by the property.
If your home value stays unchanged and you reduce your mortgage principal by an extra $1,000 using new monthly income, your home equity increases by $1,000. Compared with spending that money, your net worth is also $1,000 higher.
There is an important distinction when the payment comes from money you already own. If you move $1,000 from savings into mortgage principal, your total net worth does not immediately rise by $1,000. Your cash falls by $1,000 while your home equity rises by $1,000. You have converted a liquid asset into an illiquid one.
The long-term financial benefit comes next: a lower mortgage balance creates less future interest, assuming the loan remains outstanding. That interest saving can improve future net worth.
Before making extra payments, tell your mortgage servicer that additional funds should be applied to principal. The Consumer Financial Protection Bureau also advises checking your loan terms for any prepayment penalty. Small extra principal payments do not normally trigger one, but the contract should confirm it.
The Real Numbers: Three Extra-Payment Strategies
The following examples use a $300,000 fixed-rate mortgage at 7% for 30 years, with a regular principal-and-interest payment of approximately $1,996. Without extra payments, total interest over the full term is approximately $418,527.
| Strategy | Extra Amount | Estimated Payoff Time | Estimated Interest Saved |
| Standard monthly payment only | $0 | 30 years | $0 |
| One extra full payment per year | $1,996 annually | About 24 years | About $98,500 |
| Round monthly payment to $2,150 | About $154 monthly | About 24 years, 2 months | About $96,900 |
These figures are estimates based on the stated loan terms and assume extra funds are applied to principal. Taxes, insurance, escrow changes, refinancing and payment timing are excluded.
Strategy 1: One Extra Full Payment Per Year
Making one additional principal-and-interest payment of about $1,996 each year reduces the loan term from 30 years to approximately 24 years in this example. Total interest falls by roughly $98,500.
That is a stronger result than many homeowners expect because the interest rate is 7%. The higher the mortgage rate, the more valuable early principal reduction becomes.
A homeowner could make the extra payment using a tax refund, annual bonus or a planned savings target. The key is consistency. One extra payment in a single year helps, but repeating it annually creates the major interest reduction.
Strategy 2: Biweekly Payments
A biweekly plan collects half of the monthly mortgage payment every two weeks. According to the Consumer Financial Protection Bureau, this produces 26 half-payments per year, equivalent to 13 full monthly payments rather than 12.
In practice, this is similar to making one extra monthly payment each year. Depending on when funds are credited and applied to principal, the result may differ slightly from making one annual lump-sum payment.
Before enrolling, confirm how the servicer applies the payments and whether any fee is charged. A homeowner can often achieve a similar result with more flexibility by dividing one extra payment by 12 and adding that amount to principal each month, provided the servicer applies it correctly.
Strategy 3: Round Up Each Monthly Payment
Large extra payments are not required to make progress.
On this mortgage, rounding the monthly principal-and-interest payment from approximately $1,996 to $2,150 adds about $154 toward principal each month. Under the same assumptions, the mortgage could be paid off in approximately 24 years and 2 months, saving roughly $96,900 in interest.
This approach may feel easier than finding an extra $1,996 once a year. It also keeps the routine automatic: the higher payment becomes part of the monthly plan rather than a decision that must be repeated annually.
When Not to Pay Extra on the Mortgage
Paying extra toward a mortgage can be financially useful, but it should not automatically receive every spare dollar.
High-interest consumer debt usually comes first. Investor.gov states that eliminating high-interest debt can outperform investment strategies with less risk. Paying extra on a 7% mortgage while carrying a credit card balance at 22% generally leaves the more expensive problem untouched.
An available employer retirement match also deserves attention before aggressive mortgage prepayment. Investor.gov notes that employers may match workplace retirement contributions up to a plan limit. Skipping that available match to reduce moderate-rate mortgage debt may mean giving up compensation that could have increased retirement assets.
Liquidity matters too. Once additional cash is moved into home equity, it is no longer easily available for an emergency. Accessing it later may require borrowing or selling the home. Keep an emergency fund before sending large extra amounts toward principal.
A very low fixed-rate mortgage creates a closer decision. Someone with a mortgage rate below 4% may prefer investing additional money for long-term goals, but projected investment returns are uncertain. Paying down the mortgage provides known interest savings; investing offers possible higher growth with market risk.
How to See the Impact on Your Net Worth
Mortgage statements show your loan shrinking, but they do not show how the property fits into your complete financial position.
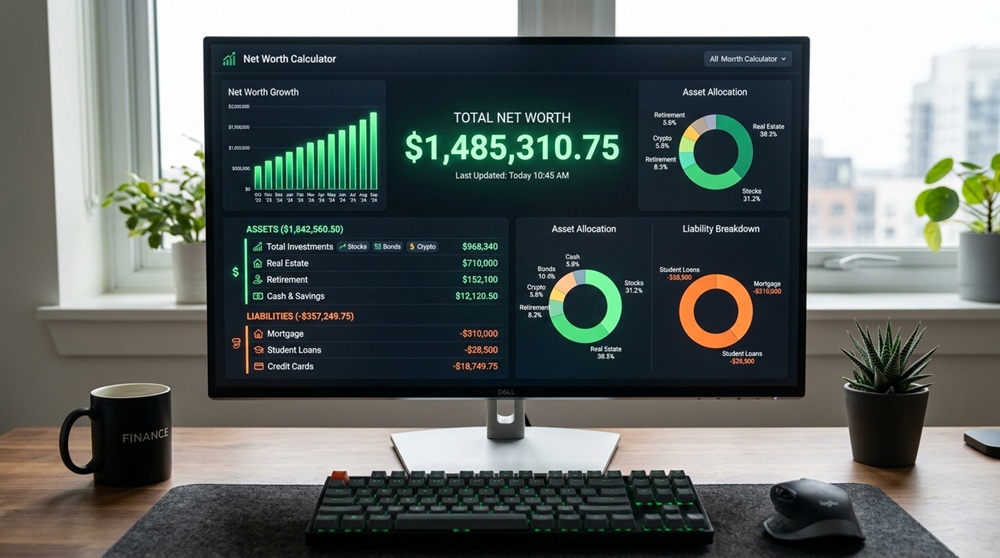
Enter your home’s current estimated market value as an asset and your remaining mortgage balance as a liability. A free net worth calculator lets you view home equity alongside cash, retirement accounts, investments and other debts, helping you see how extra principal payments affect your wider balance sheet.
Update the mortgage balance each time you calculate your net worth. Update the home’s value conservatively, perhaps once or twice a year using recent comparable sales or a reasonable current estimate. Mortgage reduction is measurable; future appreciation is not guaranteed.
For more practical resources on understanding assets, liabilities and long-term financial progress, visit NetlyWorth.
Small Extra Payments Can Create a Large Long-Term Effect
Extra mortgage payments are not magic, and they are not the right first move for every household. But once high-interest debt is controlled, an emergency reserve is available and any valuable employer retirement match is captured, additional principal can be powerful.
On a $300,000 mortgage at 7%, one extra full payment each year can remove about six years of payments and save close to $99,000 in interest under the assumptions used here. Run your numbers, confirm how your servicer applies extra payments and choose an amount you can sustain. The strongest mortgage payoff plan is the one that improves equity without weakening the rest of your financial life.